You’ve heard about the Education Freedom Tax Credit. You’re ready to give. But what happens next? Here’s every step — from writing the check to seeing the credit on your tax return.
The EFTC is a first-of-its-kind federal tax credit. Here’s how it works. Give to a qualified Scholarship Granting Organization (SGO) and receive a dollar-for-dollar federal tax credit: up to $1,700 for individuals, or up to $3,400 for married couples filing jointly. You give first; the credit reduces your federal tax bill when you file. The credit is the entry point, not the limit. You can give more, and the amount above the credit is treated like any other charitable contribution under the usual tax rules. But understanding what happens between your donation and your tax filing can make the entire process feel a lot less abstract.
Below is the complete EFTC donor timeline, broken down by season and action.
Step 1: Make Your Donation to a Qualified SGO (Anytime in 2027)
The EFTC goes into effect on January 1, 2027. From that date through December 31, 2027, any donation you make to a federally qualified Scholarship Granting Organization counts toward your EFTC credit for the 2027 tax year.
You can give once or give multiple times throughout the year. The first $1,700 of your total annual SGO donations ($3,400 for married couples filing jointly) qualifies for the dollar-for-dollar federal tax credit. The credit is the entry point, not the limit. You can give more, and the amount above the credit is treated like any other charitable contribution under the usual tax rules.
When you donate, your SGO will confirm receipt of your contribution. Save that confirmation. It’s the first piece of documentation you’ll need at tax time.
“The first $1,700 you give to a qualified SGO ($3,400 for married couples filing jointly) comes straight back off your federal tax bill, dollar for dollar. That’s not a deduction. That’s a credit.”
Step 2: Your Donation Funds a K–12 Student Scholarship (Within Weeks to Months)
After your donation is received, the SGO pools it with contributions from other donors to award scholarships to eligible K–12 students. These scholarships can cover private school tuition, home school curriculum costs, tutoring, and other qualifying educational expenses.
You don’t need to take any action during this phase. The SGO handles the student selection and scholarship disbursement process according to its own criteria and your state’s applicable rules. Most SGOs prioritize students from lower-income families, ensuring the credit reaches those who need it most.
If your SGO has a donor designation policy, you may be notified when a scholarship is awarded in connection with your gift. Otherwise, you’ll receive your formal tax documentation in early 2028.
Step 3: Your SGO Sends Tax Documentation (Early 2028)
In January or February 2028, your SGO will provide the documentation you need to claim your credit. This typically includes:
What you’ll receive from your SGO
- Written contribution acknowledgment — confirms the date and amount of your donation and that no goods or services were received in exchange.
- IRS-required substantiation — any specific form required by the IRS to validate your EFTC claim (details will be released with final IRS guidance on the credit).
- SGO certification letter — confirms that the organization is a federally qualified SGO eligible to receive EFTC contributions.
Keep these documents with your tax records. Your accountant or tax software will need them when you file your 2027 return.
Step 4: Claim Your Federal Tax Credit on Your 2027 Return (January–April 2028)
When you file your federal income taxes for the 2027 tax year — typically between January and April 2028 — you’ll report your qualified SGO donation and claim the Education Freedom Tax Credit.
The credit is applied directly against your federal income tax liability. If your credit exceeds your total tax owed for the year, you may be entitled to a refund for the difference (subject to final IRS refundability rules). Your tax professional can help you determine the maximum benefit based on your income and giving level.
“Unlike a deduction, which only reduces the income you’re taxed on, the EFTC is a credit — it reduces your actual tax bill, dollar for dollar.”
Be the First to Know
Get notified when the Education Freedom Tax Credit launches so you don’t miss the opportunity to support K–12 students while benefiting from a federal tax credit.
How the EFTC Works, Step by Step
Complete EFTC Donor Checklist
- Find a qualified SGO
- Make your donation in 2027
- Save your receipt
- Watch for tax documents in early 2028
- Work with a tax professional
- File your 2027 federal return
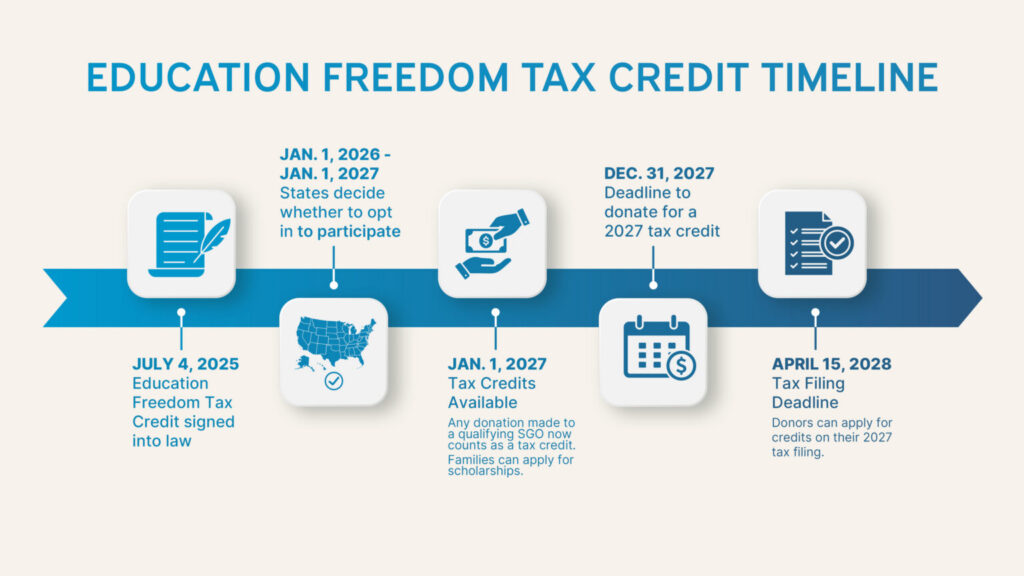
What the Full Timeline Looks Like
The visual below maps out the complete donor journey from the moment you give to the moment the credit posts on your return. The timeline is straightforward — the key is knowing which actions fall in 2027 (your donation) versus which fall in 2028 (your filing).
The Part Most Donors Don’t Realize
The EFTC has two layers of tax benefit — and most donors only hear about one of them.
Layer 1: The tax credit. The first $1,700 of your annual SGO donation ($3,400 for married couples filing jointly) qualifies for a 100% federal tax credit. A credit is not the same as a deduction. A $1,700 deduction for someone in the 22% tax bracket saves them $374. A $1,700 credit saves them $1,700 — the entire amount comes straight off their tax bill.
Layer 2: Giving beyond the credit. The credit is the entry point, not the limit. You can give more, and the amount above the credit is treated like any other charitable contribution under the usual tax rules. For example, a married couple filing jointly who gives $10,000 can claim up to $3,400 as a federal tax credit, and the remaining $6,600 is treated like any other charitable contribution. Consult your tax advisor for your situation.
Deduction value depends on your marginal tax rate and whether you itemize. Consult a qualified tax professional for guidance specific to your situation.
This combination makes the EFTC one of the most compelling philanthropic giving structures in the U.S. tax code — and the students who receive scholarships funded by your gift benefit immediately, regardless of which tax advantage applies to you.
The Education Freedom Tax Credit takes effect January 1, 2027. Donations made to qualified Scholarship Granting Organizations (SGOs) on or after that date are eligible for the tax benefits. The credit covers the first $1,700 of your annual donation, or the first $3,400 for married couples filing jointly. The credit is the entry point, not the limit. You can give more, and the amount above the credit is treated like any other charitable contribution under the usual tax rules.
Timelines vary by SGO, but most scholarship-granting organizations award and disburse scholarships within a few weeks to a couple of months of receiving a donation. Your contribution is pooled with other donations to fund scholarships on a rolling basis.
Your SGO is required to issue you a written contribution acknowledgment — similar to a charitable gift receipt — confirming the amount donated and the date. Keep this document; you will need it when you file your federal tax return to claim the Education Freedom Tax Credit.
No. The EFTC is a federal tax credit, so you can donate to any qualified SGO operating in any state and still claim the credit on your federal return. You should confirm the organization is a federally qualified SGO before donating.
Each SGO has its own policies. Some allow donors to designate a general geographic area or school type; others assign scholarships based on student applications and demonstrated financial need. Review your SGO’s policies before donating if school selection is important to you.
The first $1,700 ($3,400 for married couples filing jointly) is credited dollar for dollar. The credit is the entry point, not the limit. You can give more, and the amount above the credit is treated like any other charitable contribution under the usual tax rules. Your tax professional can help you calculate the combined benefit.