A school with campuses in two states asked a simple question: does the money have to come from in-state? The answer sits in two short passages of federal law, and it points in two different directions at once.
A school considering whether to start its own scholarship organization recently laid out its problem this way. The main campus sits in one state. A sister school is in another. The affiliated boys’ school is across a river, in a state that has not joined the federal program at all. And the alumni who would fund the whole thing live everywhere.
So which state’s rules apply?
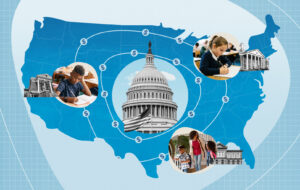
The federal statute answers both halves of that question, and the answers do not match. Donors face no residency test at all. Scholarships face a strict one. Under Section 25F of the tax code, a taxpayer in any state may give to a qualified scholarship organization listed by any participating state and claim a dollar-for-dollar federal tax credit of up to $1,700. But the organization receiving that gift may spend it only on students inside the single state that listed it.
Donations travel. Scholarships stay home.
Why the Question Confuses Some
Here’s the reason some people get this wrong. Roughly two dozen states already run their own tax-credit scholarship programs, and every one of them is built on a state tax return. To claim a state credit, you generally have to owe state tax, which means you generally have to live there. Geography is baked into the donor side.
The Education Freedom Tax Credit (EFTC) works from the opposite direction. It is a federal credit, claimed on a federal return, so the donor’s home state has no bearing on whether the credit exists.
The credit was created by the One Big Beautiful Bill Act, which became law on July 4, 2025. It takes effect for contributions made on or after January 1, 2027. You may also see it called the Federal Scholarship Tax Credit, the Educational Choice for Children Act, or simply Section 25F. Same program, different names.
What the Statute Says About Donors
Section 25F(a) makes the credit available to “an individual who is a citizen or resident of the United States.” That is the whole residency requirement.
Nothing in that language asks where the donor lives. Nothing asks whether the donor’s own state has opted in. The election that matters is the one made by the state that approved the organization, not the one printed on the donor’s driver’s license.
In practice, that means a graduate living in a state that has declined to participate may still give to a scholarship organization listed by a participating state and claim the credit on her federal return. Two separate limits still apply: the credit is capped at $1,700 per taxpayer (Treasury rules pending), and Section 25F(b)(2) reduces it by the amount of any state-level credit claimed for the same contribution. Neither has anything to do with residency.
What the Statute Says About Scholarships
Section 25F(c)(3) defines a qualified contribution as one the organization uses to fund scholarships for eligible students “solely within the State in which the organization is listed.” That one word, solely, is the geography of the entire program.
For example, an organization listed by Virginia may accept a gift from a donor in Texas and a gift from a donor in Oregon. Every dollar of both gifts can only become a scholarship for a Virginia student.
There is no provision allowing a listed organization to forward money to students in another state, however deserving those students may be. Under the statute’s own terms, a contribution spent outside the listing state is no longer a qualified contribution, which puts both the donor’s credit and the organization’s listing in question.
The Imbalance That Changes the Math for Holdout States
Put the two halves together and something uncomfortable emerges for states still deciding.
A state that has not made the federal election has no list of approved organizations. No organization anywhere can award Section 25F scholarships to that state’s students, because every award has to flow through some state’s listing.
Be the First to Know
Get notified when the Education Freedom Tax Credit launches so you don’t miss the opportunity to support K–12 students while benefiting from a federal tax credit.
Meanwhile, that state’s residents remain federal taxpayers. The $1,700 credit is available to them, and nothing in the law stops them from giving to an organization across the border.
The result is one-directional. Support flows out of a non-participating state and cannot flow in. This is not a moral point about which states are right. It is an arithmetic consequence of two statutory passages that were written to do different jobs.
What This Means for a School Network Split Across a Border
For the school that asked the original question, the answer cuts both ways.
Families at the campus in the non-participating state cannot receive scholarships funded by qualified contributions until their state joins. Their timeline belongs to their state capitol, not to the school.
Those same families, if they are federal taxpayers, may donate to fund students at the participating-state campus starting January 1, 2027. The credit does not care which side of the river they live on. Where each state currently stands is tracked on our state participation map.
What the Law Leaves Genuinely Unresolved
Here is where honesty matters more than confidence: the statute does not clearly address the multi-state organization.
Section 25F(c)(3) refers to “the State in which the organization is listed,” in the singular. Nothing in the section says whether a single entity may appear on two states’ lists, or how it would have to keep its books if it did.
The anti-commingling rule at Section 25F(c)(5)(B) already requires separate accounting for qualified contributions. It is reasonable to expect that a dual-listed organization would need something like a separate pool per state to satisfy the “solely within the State” test. That is inference drawn from the statute, not a rule Treasury has issued.
The organizational requirements in subsection (d), including the requirement to serve 10 or more students who do not all attend the same school, are written at the level of the organization rather than the campus. Even so, every individual award still has to pass through a state’s listing, so a sibling campus in a non-participating state cannot host recipients regardless of how the entity is structured.
This is exactly the kind of mechanical question Treasury’s forthcoming regulations are expected to address. As of publication, no state has opened its certification process for scholarship organizations, and Treasury has not published final rules. Until it does, the cautious plan for a two-state network is one listing per state and no promises about cross-state awards. See our preview of the Treasury guidance.
Why Fundraising Plans Are Often Sized to the Wrong Map
The practical read for anyone building a scholarship organization now is short. The donor map is the country. The scholarship map is your state.
Most fundraising plans are built for the second map. Alumni networks, out-of-state grandparents and supporters in neighboring non-participating states are all available from the first day the program operates.
One caution that has nothing to do with Section 25F: soliciting donations across state lines carries ordinary state-law obligations of its own, including charitable solicitation registration in many states. The federal statute neither creates those duties nor waives them.
Where AFC Scholarship Fund Fits, and What to Watch Next
Three things are worth watching between now and January 1, 2027. Whether Treasury’s final regulations address dual-state listings. Whether additional states complete their federal elections. And when the first states open certification so organizations can actually be listed.
If you want to understand how a gift becomes a scholarship before the program begins, start with how the Education Freedom Tax Credit works, step by step, and sign up for updates to find out where your state stands.
Based on the statute's text, yes. Section 25F(a) extends the credit to any individual who is a citizen or resident of the United States, with no requirement that the donor's own state participate. Eligible taxpayers may claim a credit of up to $1,700 for a qualified contribution to a scholarship organization listed by a participating state. Final Treasury regulations have not been published, and no contributions can be made before January 1, 2027.
Not from the same listing. Section 25F(c)(3) requires that qualified contributions fund scholarships for eligible students solely within the state that listed the organization. Whether a single entity may hold listings in two states is not addressed in the statute and is one of the open questions Treasury guidance is expected to clarify.
The statute sets no residency-based reduction. Two other limits apply: the per-taxpayer cap, and Section 25F(b)(2), which reduces the federal credit by any state-level credit claimed for the same contribution.
Not until their state makes the federal election. Every award must flow through a participating state's list of approved organizations, so a campus in a non-participating state cannot host recipients regardless of how the organization is structured.
The law took effect July 4, 2025, but qualified contributions cannot be made until January 1, 2027. As of publication, no state has opened certification for scholarship organizations and Treasury has not issued final regulations.